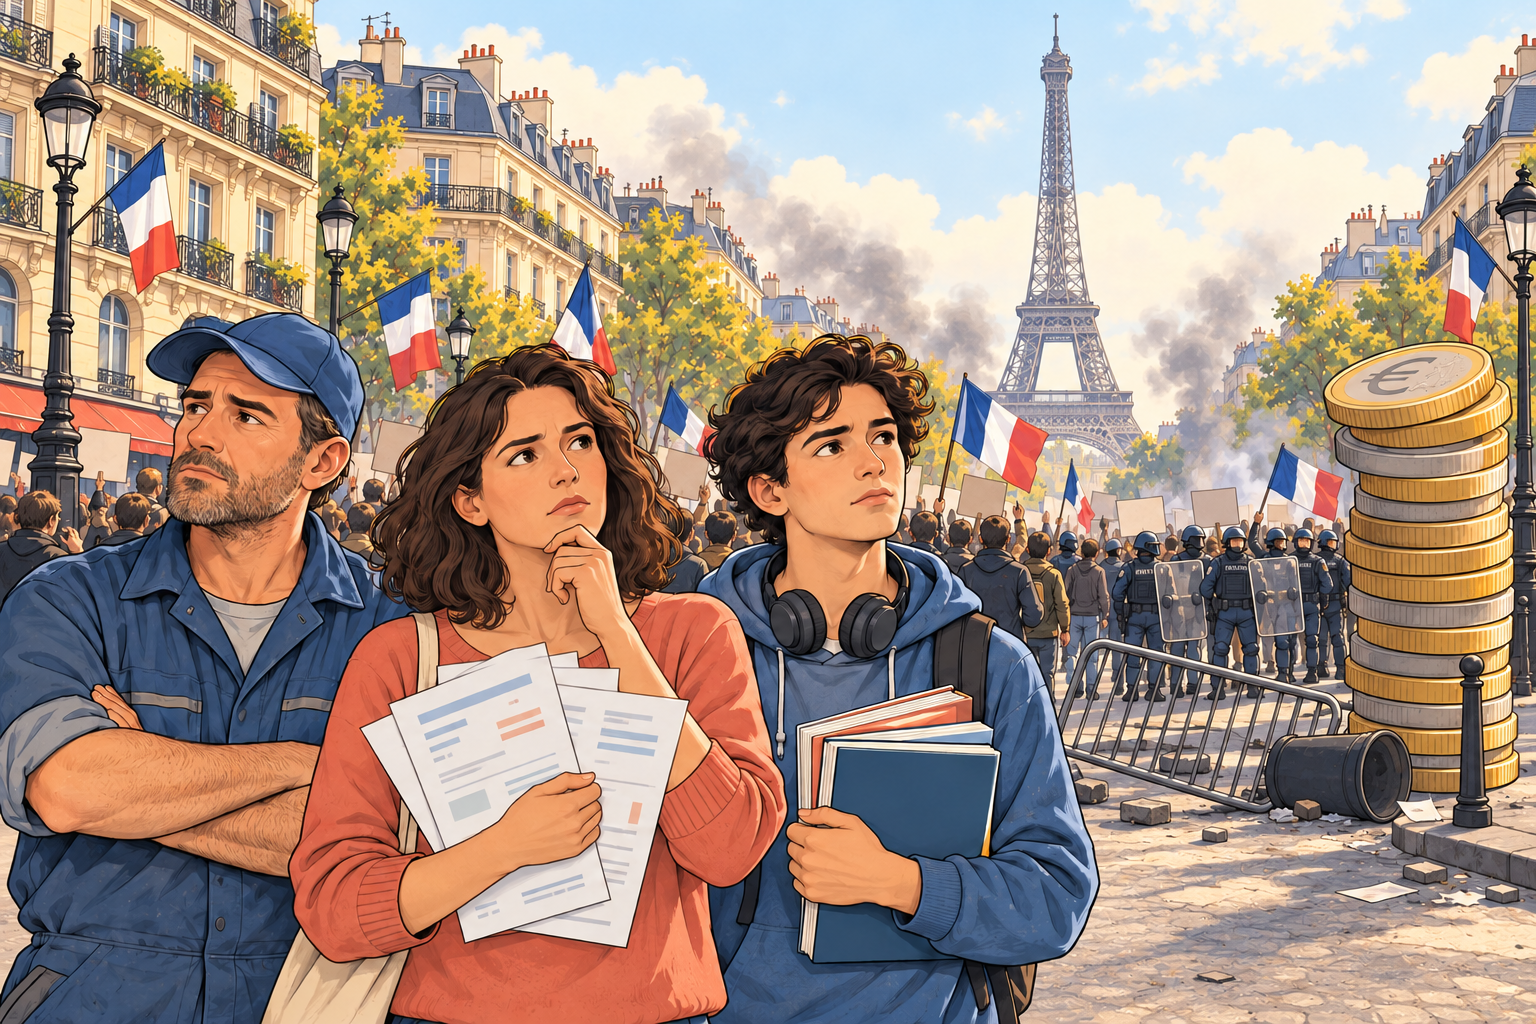
A student sees an overcrowded classroom. A parent sees higher household bills. The government sees a budget it struggles to balance.
France’s October protests brought these frustrations together. Anger over school conditions widened into demands over living costs and public services. Most demonstrators were peaceful, although violence and looting overshadowed their concerns. The immediate grievances are clear, but the economic background stretches back years.
The promise that bought Europe time
During the euro-area debt crisis, which began with Greece and spread across the currency union, European Central Bank President Mario Draghi pledged in July 2012 to do “whatever it takes” within the bank’s mandate to preserve the euro.
The ECB then outlined a programme allowing government-bond purchases without a preset quantity limit, subject to strict conditions. This was a backstop against financial panic, rather than an unconditional promise to fund government spending.
That distinction matters. Emergency action helped protect the currency union. But financial stability could not, by itself, resolve weak growth, persistent deficits or disagreements about who should pay for public services.
When cheap money makes debt look manageable
The broader era of low interest rates made borrowing less expensive. Governments could carry larger debts without an equally large increase in annual interest payments.
Think of a household with a very low mortgage rate. Its monthly payment may feel comfortable even while the outstanding loan remains substantial. The pressure becomes clearer when refinancing costs rise.
Government debt works differently, but a similar timing problem exists: higher borrowing costs gradually reach the budget as older bonds mature and new debt is issued. Money spent on interest then competes with education, infrastructure and other priorities.
Cheap credit can also support property and share prices. Asset owners may gain, while people trying to buy their first home face a higher entry price. However, this is a possible channel of inequality—not proof that ECB policy caused France’s unrest.
Borrowing bought time. How was it used?
France’s debt problem has several sources. Pandemic assistance and energy-price support protected households and businesses, but also increased borrowing. Spending pressures and weaker-than-expected revenues added to the strain.
The IMF identified large deficits associated with pandemic and energy support as the main driver of rising debt over the preceding five years, while low interest costs initially softened the impact.
The connection is therefore indirect: monetary policy influenced the cost of borrowing; fiscal decisions determined spending, taxation and the amount borrowed.
Some emergency spending was necessary. The harder question is whether governments built a durable financial position once the immediate emergencies passed.
How debt becomes a classroom problem
Public debt can seem distant from daily life. The connection becomes clearer when interest payments absorb money that could otherwise support public services.
Consider a simplified example—not France’s actual figures. A government owes €3 trillion. If the average interest rate on that debt eventually rises by one percentage point, its annual interest bill increases by €30 billion once the entire debt stock has been refinanced at the higher rate.
The adjustment takes years because existing bonds do not all mature together. Nevertheless, the pressure builds. Without stronger revenues or economic growth, the government faces difficult choices: borrow more, raise taxes or restrain spending.
This does not mean every missing teacher or delayed school repair can be blamed on debt. Spending priorities and management also matter. But a growing interest bill leaves less room to respond when citizens ask for improvements.
Why Americans should pay attention
For American readers, France raises a familiar question: what happens when voters want reliable public services, lower taxes and sustainable government finances at the same time?
Borrowing can bridge the gap temporarily. It becomes harder to sustain when interest costs grow faster than the resources available to pay them.
There is also an important difference. France shares the euro and cannot independently set monetary policy or issue its own national currency. The United States borrows in dollars and has its own central bank. Their financial constraints therefore differ, although neither country can avoid choices about resources and priorities.
The wider lesson is about using borrowed money well. Investment that improves productivity can strengthen future finances. Borrowing repeatedly to cover an unresolved gap between spending and revenue can make tomorrow’s choices more painful.
Why tax cuts became a question of trust
Under Emmanuel Macron, France replaced its broad wealth tax with a property-focused tax and introduced a flat tax on investment income. Supporters expected stronger investment and greater economic attractiveness. Critics saw advantages for wealthy households while public services remained under pressure.
Tax cuts reduce revenue unless offset by growth, other taxes or spending adjustments. Yet their eventual economic benefits cannot simply be assumed, and reversing them would not automatically close the whole budget gap.
France also collects substantial public revenue. The IMF has stressed spending efficiency alongside closing ineffective tax loopholes and improving fairness.
The argument beneath the protests
Here is one interpretation of the accumulated tension: inexpensive borrowing delayed difficult choices, gains from asset ownership were unevenly shared, and later budget restraint made the trade-offs more visible.
Imagine being told your child’s school must economise while remembering earlier tax relief for investors. Even a financially justified measure becomes politically difficult when sacrifice appears unequal.
France needs a credible way to stabilise debt, improve services and explain how the burden will be shared. For readers elsewhere, the lesson is relevant: cheap borrowing creates breathing room, but lasting stability depends on how that time is used—and whether citizens trust the choices made.